Loan Amortization Schedule
Enter the amount, the interest rate and the term, and this spreadsheet builds the full amortization schedule: every payment, how much goes to interest and principal, and the balance left after each month. It works for mortgages, car loans, student loans and personal loans.
Add an extra monthly payment to see how much sooner you would be debt-free and how much interest you would save. The payoff date and totals update instantly.
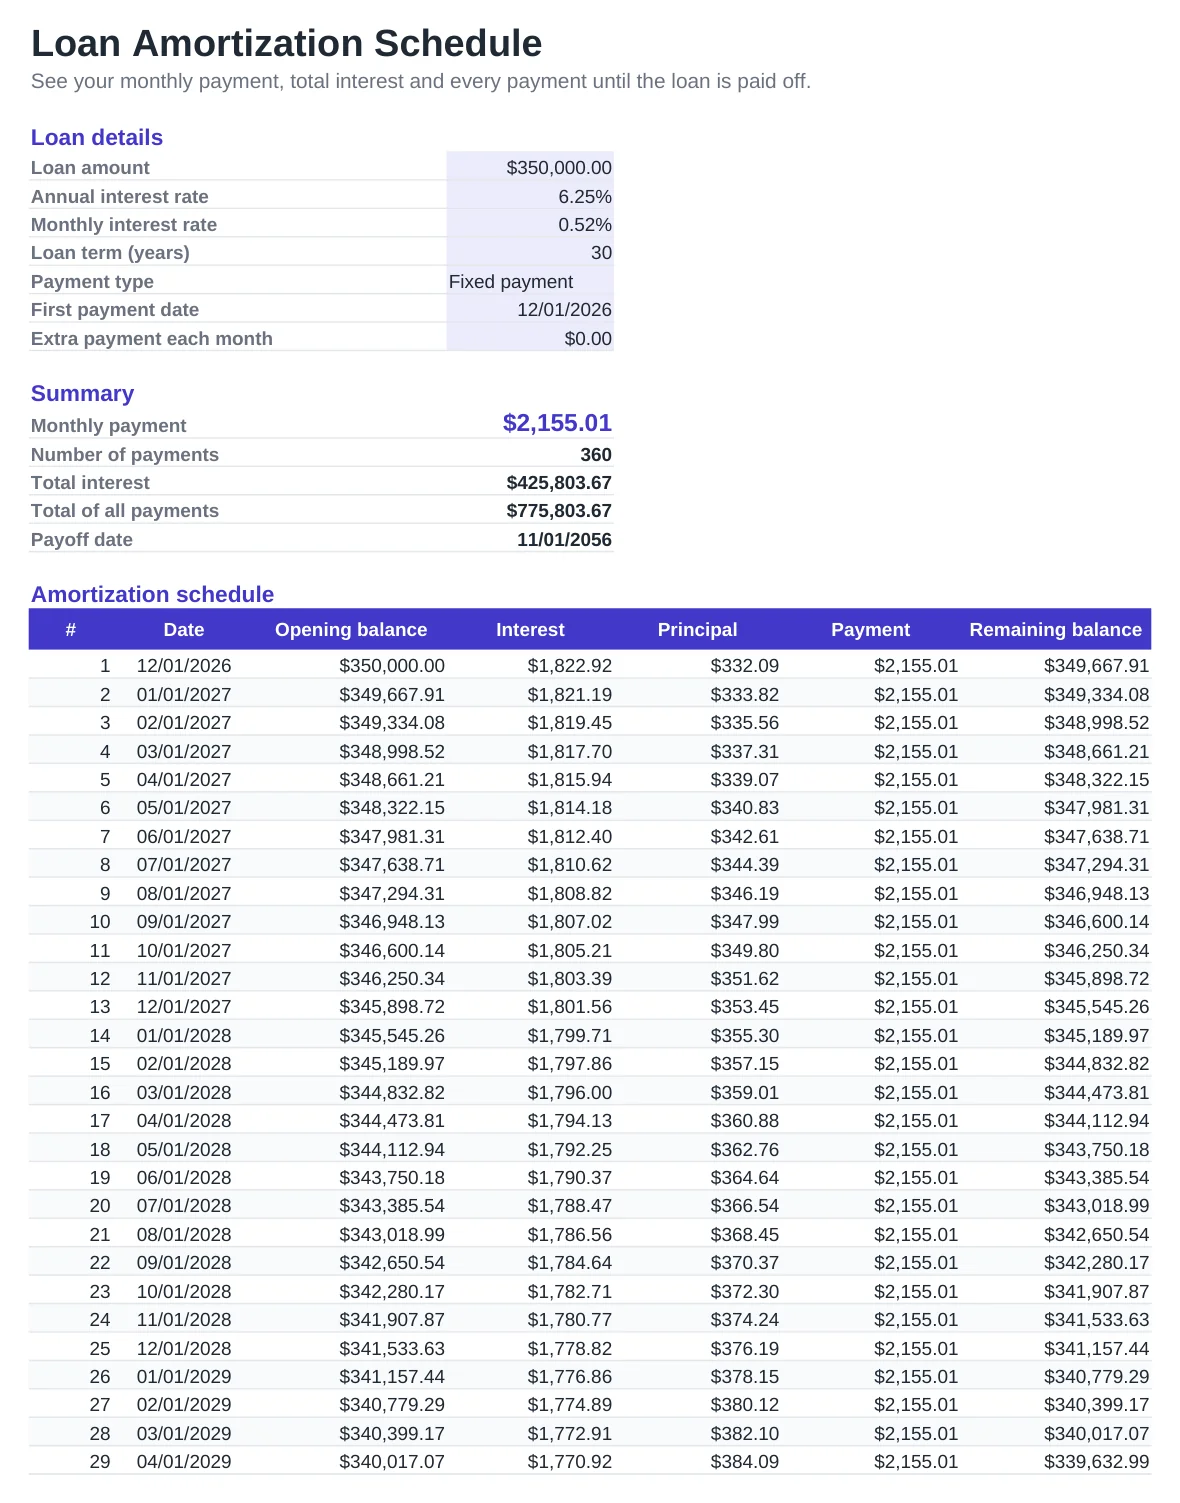
What's included
- Monthly payment calculated from amount, APR and term
- Full schedule with interest, principal and remaining balance for up to 40 years
- Extra monthly payment field that shortens the loan and shows the interest saved
- Choice of fixed payments or equal principal payments
- Summary with number of payments, total interest, total cost and payoff date
How to use it
- Enter the loan amount and the annual interest rate.
- Set the term in years and the date of your first payment.
- Leave the payment type on Fixed payment for a standard mortgage or car loan.
- Try an extra monthly payment and watch the payoff date move.
- Use the schedule to check your lender's statement or compare offers.
Getting more out of a loan schedule
On a 30-year mortgage, most of each early payment is interest. That is why small extra payments early on cut the total cost so much: every extra dollar reduces the balance that interest is charged on for the rest of the loan.
Compare loans on the APR, which includes fees, not only the note rate. A 15-year term usually has a lower rate and far less total interest, at the price of a higher monthly payment.
Remember that your real monthly housing cost also includes property tax, homeowners insurance and possibly PMI or HOA dues, which this schedule leaves out.
Frequently asked questions
Is this amortization schedule free?
Yes. Download it, edit it and use it as often as you like, with no sign-up.
Can I use it for a car loan or personal loan?
Yes. Any loan with a fixed rate and monthly payments works. Enter the amount, rate and term in years, for example 5 for a 60-month car loan.
How do extra payments work in the sheet?
The extra amount is added to the principal each month. The balance falls faster, the loan ends sooner and the total interest drops.
Why doesn't the payment match my lender exactly?
Lenders round to the cent and may use a slightly different day count. The difference is usually a few cents. Escrow for taxes and insurance is not included here.